
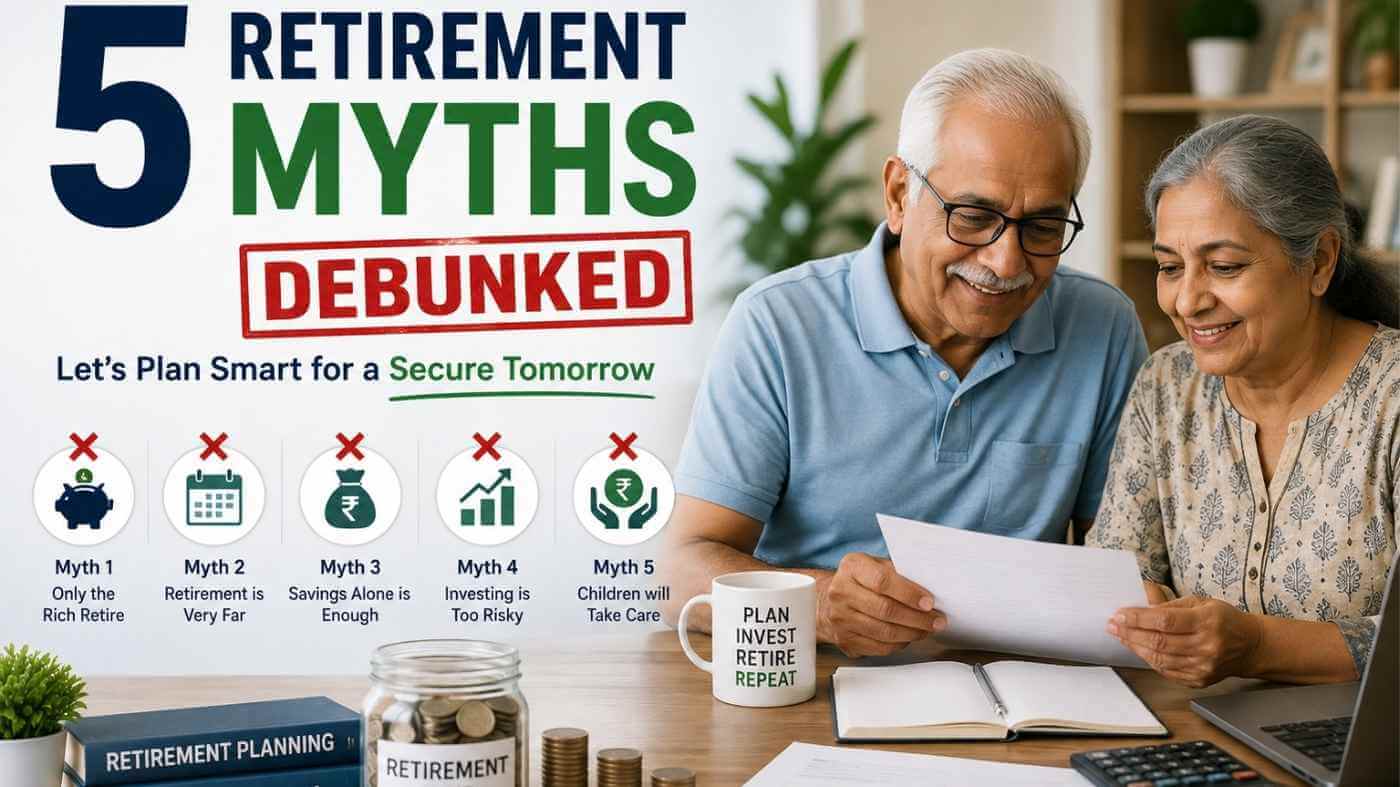
Retirement myths in India are more dangerous than most people realise. They quietly convince otherwise sensible individuals to delay saving, depend on others, or assume that “something will work out.” By the time reality sets in, the window for building a solid retirement corpus has already narrowed. In this guide, we debunk five of the most persistent myths about retirement planning in India, so you can make clearer decisions and take action while you still have time on your side.
Whether you are 25 and just starting, or 45 and wondering if it is too late, understanding what is true and what is not can completely change how you approach your financial future.
Why Retirement Myths in India Are So Harmful
India does not have a universal pension system that covers every working citizen. Most private sector employees, freelancers, and small business owners are entirely responsible for funding their own retirement. Yet a majority of Indians enter their 60s with little to no dedicated retirement savings.
A large part of the problem is not a lack of income. It is a set of deeply held beliefs that discourage action. These beliefs feel logical on the surface, which is exactly what makes them so risky. Let us take each myth apart one by one.
Retirement Myth 1: My Children Will Take Care of Me
This is perhaps the most common retirement myth in India, and also the most emotionally loaded. The assumption that family will provide for you in old age is deeply rooted in Indian culture. However, financial realities in modern India are shifting fast.
Why This Thinking Can Leave You Vulnerable
Your children will have their own EMIs, school fees, medical costs, and career pressures to manage. Expecting them to fully fund your retirement places a significant burden on them, and it can damage the very relationship you are counting on.
More practically, what if your child moves abroad? What if they face a job loss or a health emergency of their own? Financial dependence on children is a plan built on assumptions, not certainty.
The healthier approach is to build your own retirement fund so your children remain a bonus, not a necessity. That is a gift to them as much as it is a plan for you.
- Urban Indians increasingly live in nuclear families, not joint households.
- Cost of living is rising faster than salaries in many cities.
- Your children’s financial obligations will grow, not shrink, over time.
- Financial independence in retirement protects your dignity and your relationships.
Retirement Myth 2: I Will Start Saving for Retirement Later
“I am only 30. I have decades ahead.” This is one of the most costly retirement myths Indians carry. The belief that retirement planning is something you do in your 40s or 50s ignores the single most powerful force in investing: compounding.
The Real Cost of Waiting
Consider two investors, Priya and Rahul. Priya starts a SIP of Rs. 5,000 per month at age 25 and continues until 60. Rahul starts the same SIP at 35, also until 60. Assuming a 12% annual return, the difference in their retirement corpus is not marginal. It is massive.
| Investor | Start Age | Monthly SIP | Duration (Years) | Approx. Corpus at 60 |
|---|---|---|---|---|
| Priya | 25 | Rs. 5,000 | 35 | Rs. 3.24 crore |
| Rahul | 35 | Rs. 5,000 | 25 | Rs. 94.88 lakh |
Same monthly investment. The only difference is the starting age. Priya ends up with more than three times Rahul’s corpus. This is the power of starting early.
Even if you start late, starting now is always better than waiting another year. The best time to plant a tree was 20 years ago. The second best time is today.
Retirement Myth 3: My EPF and PPF Are Enough for Retirement
Many salaried Indians feel reassured knowing their EPF deduction happens automatically every month. Add a PPF account to the mix, and they feel their retirement is covered. This is one of the most widespread retirement myths among the Indian middle class.
The Problem with Relying Only on EPF and PPF
EPF and PPF are excellent instruments. They are safe, tax-efficient, and disciplined. However, they come with limitations that most people overlook.
- Returns are fixed and modest: EPF currently earns around 8.15% per annum. PPF earns around 7.1%. While these are safe returns, they may not beat inflation over a 25- to 30-year retirement period.
- PPF has investment limits: You can invest a maximum of Rs. 1.5 lakh per year in PPF. That is Rs. 12,500 per month. For most people, this alone will not build a sufficient corpus.
- EPF depends on employment: Freelancers, business owners, and those with career gaps do not always have consistent EPF contributions.
- Inflation erodes purchasing power: At 6% average inflation, Rs. 50,000 today will have the purchasing power of roughly Rs. 14,000 in 20 years.
What a Balanced Retirement Portfolio Looks Like
A smarter approach combines EPF and PPF with equity mutual funds through SIPs. Over a long horizon of 15 to 30 years, equity mutual funds have historically delivered returns that comfortably beat inflation and grow real wealth.
The right mix of instruments depends on your age, income, risk appetite, and when you plan to retire. There is no single formula that fits everyone, which is precisely why personalised guidance makes such a difference.
Retirement Myth 4: Retirement Planning Needs a Lot of Money to Start
A surprising number of Indians believe retirement planning is only for the wealthy. “I will start once I earn more,” or “I cannot afford to invest right now,” are phrases that delay action for years, sometimes decades. This is a retirement myth that costs ordinary investors the most.
You Can Start with as Little as Rs. 500 a Month
Thanks to SIPs in mutual funds, you can start investing for retirement with amounts as small as Rs. 500 per month. This is not a token gesture. Over time, even a small and consistent investment can grow into something meaningful.
The key is consistency and time, not the size of your initial investment. As your income grows, you can increase your SIP amount gradually. Even a 10% annual step-up in your SIP amount can dramatically increase your retirement corpus.
The Step-Up SIP Advantage
Suppose you start a SIP of Rs. 3,000 per month at age 30 and increase it by 10% every year. By age 60, your monthly contribution will have grown to around Rs. 52,000. Your total investment over 30 years will be roughly Rs. 59 lakh, but your estimated corpus at 12% annualised returns could cross Rs. 3 crore.
This is not magic. It is math. And it is accessible to anyone with a regular income, no matter how modest.
Retirement Myth 5: I Can Figure Out Retirement Planning on My Own
With apps, calculators, and financial content available online, many investors believe they have everything they need to plan their own retirement. While financial literacy is genuinely important, the belief that you can do it all alone overlooks some critical blind spots.
Why DIY Retirement Planning Often Falls Short
Retirement planning is not just about picking funds. It involves understanding your actual retirement needs, estimating inflation-adjusted expenses, calculating the corpus you need, choosing the right asset allocation, rebalancing over time, and eventually withdrawing in a tax-efficient way.
Most people do one or two of these well. Very few do all of them consistently over 25 to 30 years without making costly mistakes.
- Many investors panic-sell during market corrections, locking in losses just before recovery.
- Asset allocation mistakes, such as staying in only debt funds or only equity funds, can significantly reduce long-term wealth.
- Tax implications of withdrawals are often ignored until it is too late.
- Without accountability, SIPs often get paused or stopped during tough months.
The Value of a Trusted Guide
The real difference between investors who retire comfortably and those who struggle is rarely about the specific funds they chose. It is about having a clear, consistent plan and someone to help them stick to it through life’s ups and downs.
At VSJ FinMart, we work with each client to understand their retirement goals, timeline, and risk comfort before recommending any mutual fund investment strategy. Rather than offering a generic solution, we help you build a personalised retirement plan that evolves with you. If you have been putting this off, a single conversation is often all it takes to get started with clarity.
How to Start Your Retirement Plan: Practical Steps
Now that the myths are out of the way, here is a clear, practical path forward. You do not need to do everything at once. Start where you are and build from there.
- Estimate your retirement expenses: Think about the lifestyle you want at retirement. Factor in housing, healthcare, travel, and daily living costs. Adjust for inflation over your remaining working years.
- Calculate your target corpus: A common rule of thumb is the 25x rule. Multiply your expected annual retirement expenses by 25 to get a rough target corpus. Refine this with a financial advisor.
- Start a SIP today: Even a small SIP started today is better than a large one planned for next year. Set up an automatic investment so you never miss a month.
- Diversify your instruments: Combine equity mutual funds for growth with debt instruments for stability. The right ratio changes with your age.
- Review annually: Revisit your plan at least once a year. Adjust your SIP amounts as your income grows and rebalance your portfolio if needed.
- Do not touch your retirement fund: Avoid the temptation to dip into your retirement savings for other goals. Keep this money separate and purposeful.
Retirement Planning Tools Worth Knowing
India offers several tax-efficient instruments specifically designed for retirement. Each has its own strengths.
| Instrument | Best For | Approx. Returns | Tax Benefit | Liquidity |
|---|---|---|---|---|
| EPF | Salaried employees | ~8.15% p.a. | EEE (80C) | Low (restricted withdrawals) |
| PPF | Long-term safe saving | ~7.1% p.a. | EEE (80C) | Low (15-year lock-in) |
| NPS | Additional tax saving + retirement | 8–10% (market-linked) | 80CCD(1B) extra Rs. 50,000 | Low (till retirement) |
| Equity Mutual Funds (SIP) | Long-term wealth creation | 10–14% historical avg. | LTCG above Rs. 1.25 lakh taxed at 12.5% | High (can redeem anytime) |
| Debt Mutual Funds | Stability near retirement | 6–8% p.a. | Taxed as per slab | Moderate |
No single instrument is the right answer. A well-designed retirement plan typically uses a combination of two or three of these, in proportions that suit your specific situation.
Final Words: Stop Believing the Myths and Start Building
The five retirement myths we have covered, from relying on your children to assuming EPF is enough, all have one thing in common. They make inaction feel reasonable. They give you a reason to wait. And waiting is the one thing you genuinely cannot afford to do.
Retirement planning in India is not just for the wealthy or the financially savvy. It is for anyone who wants to live with dignity and independence after their working years. The tools exist. The instruments are accessible. The knowledge is available.
What most people need is a clear, personalised plan and the confidence to follow it. At VSJ FinMart, we help investors at every stage of life cut through the confusion, set realistic goals, and build a retirement strategy that works for their unique situation. You have worked hard for your money. Let it work just as hard for your retirement.
Frequently Asked Questions
1. How much should I save for retirement in India?
A practical starting point is the 25x rule: multiply your expected annual expenses at retirement by 25 to get a rough corpus target. For example, if you expect to spend Rs. 60,000 per month (Rs. 7.2 lakh per year), your target corpus would be around Rs. 1.8 crore. However, this is a simplified estimate. Inflation, healthcare costs, and your actual lifestyle goals can all change the number significantly.
2. Is it too late to start retirement planning at 45?
No, it is not too late. Starting at 45 still gives you 15 to 20 years of compounding. The strategy changes: you may need to invest more aggressively, step up your contributions faster, and be more disciplined about not withdrawing. A higher monthly SIP combined with equity mutual funds and NPS can still build a meaningful corpus by retirement age.
3. Is EPF enough for retirement in India?
EPF is a solid foundation, but it is rarely sufficient on its own. Returns from EPF may not fully beat long-term inflation, and the corpus depends heavily on your salary and years of service. Most financial planners recommend supplementing EPF with equity mutual funds, NPS, or PPF to build a more complete retirement fund.
4. What is the safest way to invest for retirement in India?
Safety in retirement planning means balancing growth and stability. When you are young, a higher allocation to equity mutual funds through SIPs gives your money room to grow. As you approach retirement, you gradually shift toward debt funds, PPF, and fixed-income instruments to protect what you have built. This shift in asset allocation over time is called a lifecycle or glide path strategy.
5. How does a financial advisor help with retirement planning?
A financial advisor helps you set a realistic retirement goal, choose the right mix of instruments, and stay invested through market ups and downs. More importantly, they help you avoid costly mistakes like panic-selling during corrections or under-saving because you assumed other income sources would be enough. Personalised advice is almost always more effective than a generic plan found online.
Disclaimer
The information provided in this blog is for educational and informational purposes only and should not be construed as investment advice. Please consult a qualified financial advisor before making any investment decisions. Shashikant Chanderkumar Mudaliar (ARN: 319377), operating under the brand name VSJ FinMart, is an AMFI-registered Mutual Fund Distributor (MFD) and does not provide investment advisory services. Mutual fund investments are subject to market risks. Past performance is not indicative of future results. Please read all scheme-related documents carefully before investing. Registration details can be verified at www.amfiindia.com/locate-distributor.
════════════════════════════════════════
SEO META INFO  (RankMath)
════════════════════════════════════════


                       (154 characters)
Focus Keyword:         retirement myths India
Secondary Keywords:    retirement planning India, how to save for retirement India, EPF enough for retirement, SIP for retirement

Word Count (approx):   2,190 words