
Most investors start with good intentions. They open a mutual fund account, make a few investments, and then wait. But without a clear plan to achieve your portfolio goals, even the most enthusiastic investors drift off course. Markets move up and down, life changes, and before long, the original goal feels distant. The good news is that staying on track is not complicated. It takes the right framework, a few smart habits, and the discipline to follow through. In this guide, you will find five proven ways to build and protect a portfolio that actually delivers on what you set out to do.
Why Most Investors Struggle to Achieve Their Portfolio Goals
The problem is rarely a shortage of money. Most people struggle because they invest without a destination in mind. They pick funds based on recent returns, follow tips from friends, or react to every market headline. This approach produces inconsistent results and a lot of unnecessary stress.
Research consistently shows that investor behaviour, not market performance, is the biggest obstacle to long-term wealth creation. Buying high out of excitement and selling low out of fear destroys returns far more than any market crash ever could.
In addition, many investors confuse activity with progress. They switch funds frequently, chase new themes, and mistake busyness for strategy. The investors who actually reach their goals tend to do less, not more.
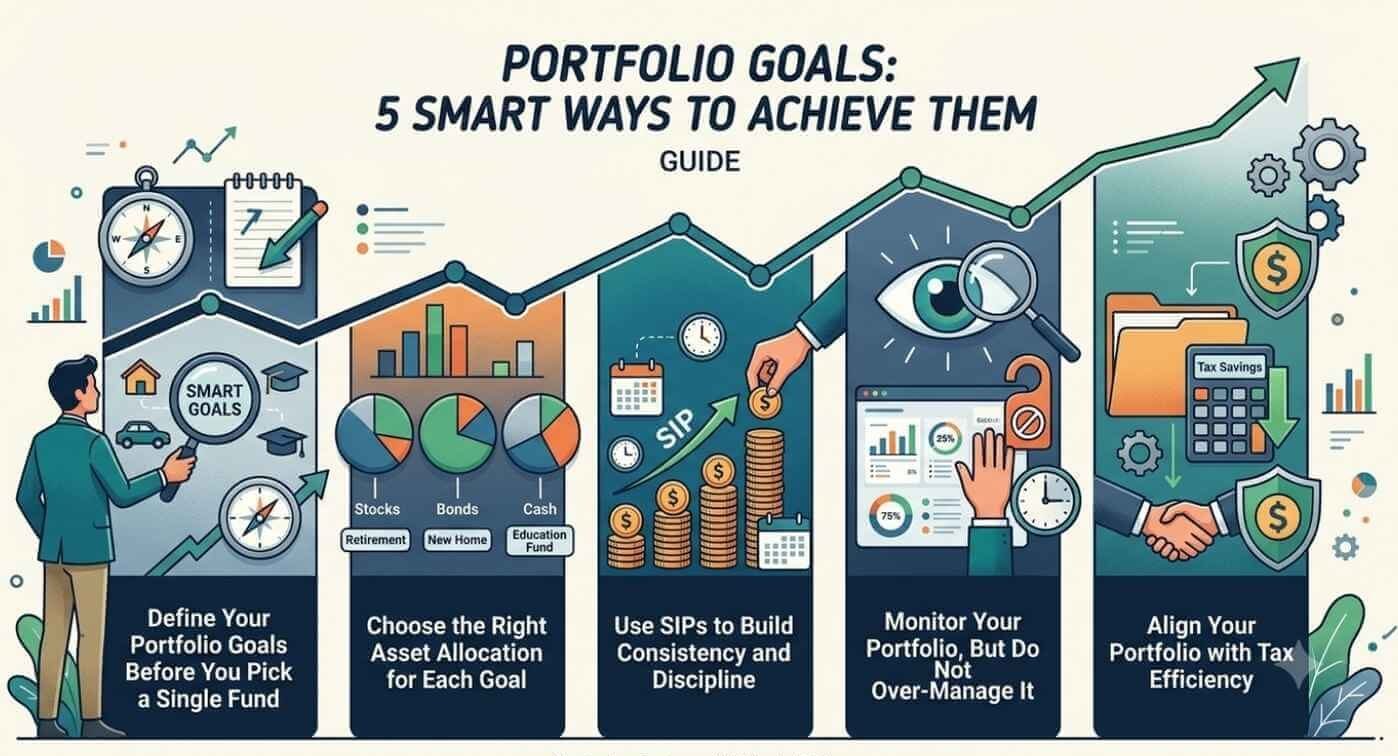
Step 1: Define Your Portfolio Goals Before You Pick a Single Fund
You cannot achieve your portfolio goals if you have not clearly defined what those goals are. A goal is not just a number. It has three parts: a purpose, an amount, and a timeline.
The Three Parts of a Clear Investment Goal
- Purpose: What is the money for? Retirement, your child’s education, a home purchase, or financial independence?
- Amount: How much do you need at the end? Work backwards from the future cost, not the present one.
- Timeline: How many years do you have? This determines your risk capacity and the type of funds suitable for you.
For example, if you want to build a corpus of Rs. 50 lakh for your child’s college education 12 years from now, that is a specific, measurable goal. You can now choose funds and SIP amounts that align with this target. Without this clarity, you are simply guessing.
Goal Buckets: A Practical Way to Organise
Most investors have more than one goal running at the same time. A useful approach is to separate your investments into goal buckets. Each bucket has its own fund selection, risk level, and time horizon. This prevents you from accidentally using long-term money for a short-term need, or vice versa.
Common goal buckets for Indian investors include:
- Emergency fund (liquid funds, 3–6 months of expenses)
- Short-term goals under 3 years (conservative hybrid or short-duration debt funds)
- Medium-term goals of 3–7 years (balanced advantage or hybrid equity funds)
- Long-term goals over 7 years (equity mutual funds, index funds)
Step 2: Choose the Right Asset Allocation for Each Goal
Asset allocation is the single most powerful decision you make as an investor. It determines how much of your portfolio sits in equity, debt, and other assets. Studies show that asset allocation accounts for more than 90% of long-term portfolio returns. Picking the right funds matters far less than getting the allocation right.
A Simple Asset Allocation Framework
| Goal Timeline | Suggested Equity % | Suggested Debt % | Risk Level |
|---|---|---|---|
| Under 1 year | 0% | 100% | Very Low |
| 1–3 years | 10–20% | 80–90% | Low |
| 3–5 years | 30–50% | 50–70% | Moderate |
| 5–7 years | 60–70% | 30–40% | Moderate to High |
| 7+ years | 80–100% | 0–20% | High |
However, these are general starting points. Your actual allocation should reflect your personal risk appetite, income stability, existing liabilities, and emotional comfort with market swings. Two investors with the same 10-year timeline may need very different allocations depending on their circumstances.
The Role of Rebalancing
Markets constantly shift your allocation away from the target. For example, if equity markets rise sharply, your portfolio may drift from a 70:30 equity-debt mix to an 85:15 mix. This increases your risk beyond what you originally planned. Rebalancing, which means periodically selling the overweight asset and adding to the underweight one, brings your portfolio back in line. Most investors should rebalance at least once a year or whenever any asset class drifts more than 5–10% from its target.
Step 3: Use SIPs to Build Consistency and Discipline
One of the most reliable ways to achieve your portfolio goals is to invest through a Systematic Investment Plan, or SIP. A SIP automatically deducts a fixed amount from your bank account every month and invests it in your chosen mutual fund. This removes emotion from the equation entirely.
Why SIPs Work So Well
- Rupee cost averaging: You buy more units when markets fall and fewer units when markets rise. Over time, your average cost per unit stays lower than the average price over the same period.
- Power of compounding: Small, regular investments grow significantly over long periods. A SIP of Rs. 5,000 per month in an equity fund growing at 12% per annum becomes approximately Rs. 50 lakh in 20 years.
- Behavioural discipline: Because the SIP runs automatically, you are not tempted to time the market or skip investments during volatile periods.
- Flexibility: You can start small and increase your SIP amount as your income grows. This approach, known as a Step-Up SIP, accelerates your wealth creation without straining your current budget.
A Practical SIP Example
Suppose Priya, a 30-year-old working professional in Pune, wants to retire comfortably at 60. She starts a SIP of Rs. 8,000 per month in a diversified equity mutual fund. Assuming a 12% annualised return, she builds a corpus of approximately Rs. 2.8 crore over 30 years. If she had waited even five years to start, the same SIP would produce roughly Rs. 1.5 crore at the same return rate. Time in the market matters enormously.
Step 4: Monitor Your Portfolio, But Do Not Over-Manage It
There is a common mistake investors make once their SIPs are running: they check their portfolio every day. Daily monitoring leads to emotional decisions. A 5% fall in your portfolio value looks alarming on screen but is perfectly normal in equity markets. Investors who react to every short-term move almost always end up worse off than those who stay put.
How Often Should You Review?
A simple review schedule works well for most investors:
- Monthly: Confirm your SIPs are running. No other action needed.
- Quarterly: Check that your portfolio allocation has not drifted significantly from target.
- Annually: Do a full portfolio review. Check fund performance against its benchmark and category peers. Rebalance if required. Review whether your goals or timelines have changed.
- At major life events: Marriage, a new child, a job change, or a large purchase should all prompt a portfolio review.
When to Switch a Fund
Switching funds is appropriate only under specific circumstances, not simply because markets are down. Consider switching when:
- A fund consistently underperforms its category average over three or more years.
- The fund manager changes and the new manager’s track record is unclear.
- The fund’s strategy or category has changed in a way that no longer matches your goal.
- Your own goal or time horizon has changed significantly.
Most importantly, never switch a fund just because a friend or colleague is talking about a newer, flashier option. Chasing recent returns is one of the fastest ways to derail a well-built portfolio.
Step 5: Align Your Portfolio with Tax Efficiency
Taxes quietly erode investment returns if you do not plan for them. A tax-efficient portfolio keeps more of your money compounding over time. Understanding how mutual fund gains are taxed in India helps you make smarter decisions about when and how to invest.
Mutual Fund Taxation at a Glance
| Fund Type | Holding Period | Tax on Gains |
|---|---|---|
| Equity Mutual Funds | Under 1 year (STCG) | 20% |
| Equity Mutual Funds | Over 1 year (LTCG) | 12.5% (above Rs. 1.25 lakh) |
| Debt Mutual Funds | Any holding period | As per income tax slab |
| ELSS Funds | 3-year lock-in | LTCG rules, tax benefit under Sec 80C |
Three Tax-Smart Habits for Investors
- Hold equity funds for at least one year to qualify for the lower long-term capital gains tax rate instead of the short-term rate.
- Use ELSS funds as part of your Section 80C tax-saving strategy. You get both a tax deduction and equity market exposure in a single investment.
- Harvest tax losses smartly. In years where some funds have lost value, redeeming them and reinvesting locks in a loss that can offset taxable gains from other redemptions in the same financial year.
Tax planning and investment planning are not separate activities. The best portfolios integrate both. If you find it hard to track all of this on your own, working with a trusted advisor who understands your full financial picture can make a significant difference.
The Role of Personalised Guidance in Reaching Your Goals
There is no shortage of generic advice online. You can find lists of top-rated funds, YouTube videos about asset allocation, and apps that claim to build portfolios automatically. However, none of these tools know your actual situation.
They do not know that you are planning to take a career break in two years, or that your parents depend on you financially, or that you have a moderate risk appetite despite a 15-year horizon. Reaching your portfolio goals in the real world requires a plan that accounts for all of these personal details.
At VSJ FinMart, we work with investors to build personalised, goal-based mutual fund portfolios that reflect your actual life, not just a generic template. Whether you are just starting or looking to restructure an existing portfolio, the right guidance can help you invest with clarity and confidence.
Final Words: Start Today, Stay the Course
The path to achieving your portfolio goals is not about finding secret funds or timing the market perfectly. It is about clarity of purpose, disciplined execution, and patience. Define your goals clearly. Allocate your assets thoughtfully. Invest regularly through SIPs. Review your portfolio without reacting to every fluctuation. And make your investments work as tax-efficiently as possible.
Every one of these steps is within your reach. The investors who reach their financial goals are not necessarily the most knowledgeable or the most aggressive. They are the ones who start early, stay consistent, and make fewer emotional mistakes along the way.
If you would like help building a mutual fund portfolio that is tailored to your specific goals and timeline, the team at VSJ FinMart is here to guide you. A short conversation can help you move from uncertainty to a clear, actionable investment plan.
Frequently Asked Questions
1. How do I know if my portfolio is on track to meet my goals?
The simplest way is to review your portfolio annually and compare your current corpus against the projected value needed at your target date. If you are below target, consider increasing your SIP amount or extending your timeline. A financial advisor can help you run these projections accurately.
2. How many mutual funds should I hold in my portfolio?
More funds do not automatically mean better diversification. For most investors, 4 to 6 carefully selected mutual funds across different categories are enough to build a well-diversified portfolio. Holding too many funds often leads to overlap and makes your portfolio harder to monitor.
3. Should I stop my SIP when markets fall sharply?
No. Stopping a SIP during a market downturn is one of the most common and costly mistakes investors make. A falling market means your SIP buys more units at lower prices, which benefits you significantly when markets recover. Staying invested through volatility is a core part of the strategy.
4. What is the ideal SIP amount to achieve long-term portfolio goals?
There is no single answer because it depends entirely on your goal, timeline, and expected returns. As a starting point, calculate the future value you need, work backwards using an SIP calculator, and arrive at the monthly amount required. Starting with whatever you can afford today and increasing it annually is a practical approach for most investors.
5. Is it better to invest a lump sum or through SIPs to achieve portfolio goals?
Both approaches have their place. SIPs work best for regular income earners who invest monthly. Lump sum investments are useful when you receive a bonus, inheritance, or any large one-time inflow. In volatile markets, investing a lump sum in tranches over 6 to 12 months reduces timing risk. Your advisor can help you decide the right approach for your situation.
Disclaimer
The information provided in this blog is for educational and informational purposes only and should not be construed as investment advice. Please consult a qualified financial advisor before making any investment decisions. Shashikant Chanderkumar Mudaliar (ARN: 319377), operating under the brand name VSJ FinMart, is an AMFI-registered Mutual Fund Distributor (MFD) and does not provide investment advisory services. Mutual fund investments are subject to market risks. Past performance is not indicative of future results. Please read all scheme-related documents carefully before investing. Registration details can be verified at www.amfiindia.com/locate-distributor.